

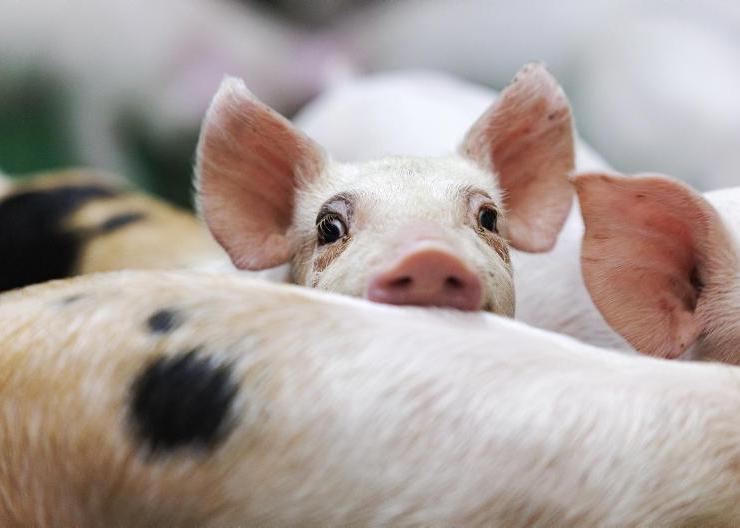
I went to a farm meeting the other evening where we were told that the average Irish pig producer was expected to lose half a million euro this year. Volatility such as this and wild swings in profitability have long characterised the Irish pig sector.
It is no wonder that there are now less than 300 commercial producers in the country, with hardly any west of the Shannon.
The huge gains in pig production efficiency have gone straight down the chain to processors, supermarkets and consumers.
The current crisis can be blamed on African Swine Fever preventing the largest exporter in the EU, Spain, going to the Chinese market and so driving down prices across Europe.
But pigmeat is just another example of producers taking the full brunt of market fluctuations.
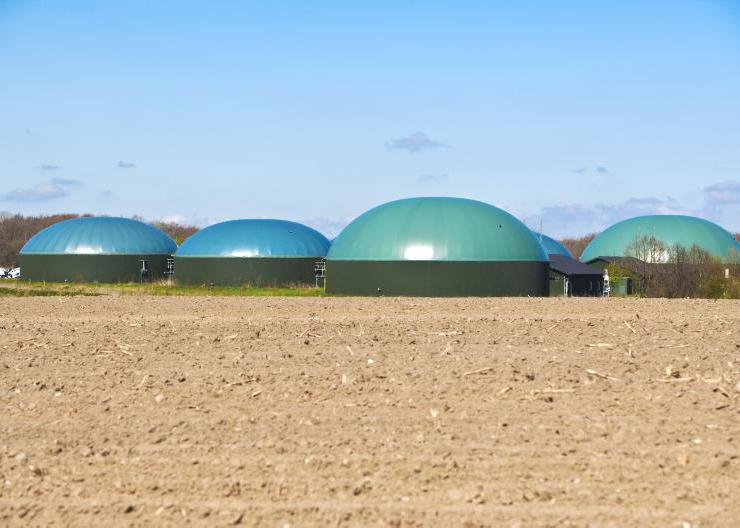
The contrast with, for example, renewable energy producers could hardly be greater where they are guaranteed an inflation-linked, long-term return on their investment.
While energy is clearly important, food is vital.
One of the problems from a farmer’s viewpoint is that once an investment in a production system is made, there is no option but to produce once the direct cash outgoings are covered, so over years, plant and livestock numbers can be run down and it’s when the question of “generational renewal” arises and there is nobody around to take over, that the penny drops.
There is no reason why a system providing some level of guaranteed returns cannot be put in place.
We had such a system in Europe which has been effectively dismantled, but elsewhere in the world, government policy has evolved to cope with these realities.
We are used to the concept of a revenue insurance model in the United States of America, but I had not realised until the other day that this year, the US intends to use 40% of its entire maize crop to produce ethanol as an additive to petrol.
They are also ramping up the use of soya bean oil as an additive in diesel.
We have so far seen no real initiatives from the EU as the CAP talks are due to reach a crunch point over the coming months.
The compulsory incorporation of maize- derived ethanol and soya-derived biodiesel in the US, as well as sugar cane derived ethanol in Brazil, are providing real markets for farm output.
Europe has been half-hearted in developing a biofuel policy while it has dismantled both its intervention system as well as meaningful protection against imports in most products.
The present EU Commissioner for Agriculture Christophe Hansen is clearly well-intentioned but at this stage, he lacks the financial fire power as well as the policy framework to prevent a continuing downward drift in European farm output and farm family well being.


SHARING OPTIONS