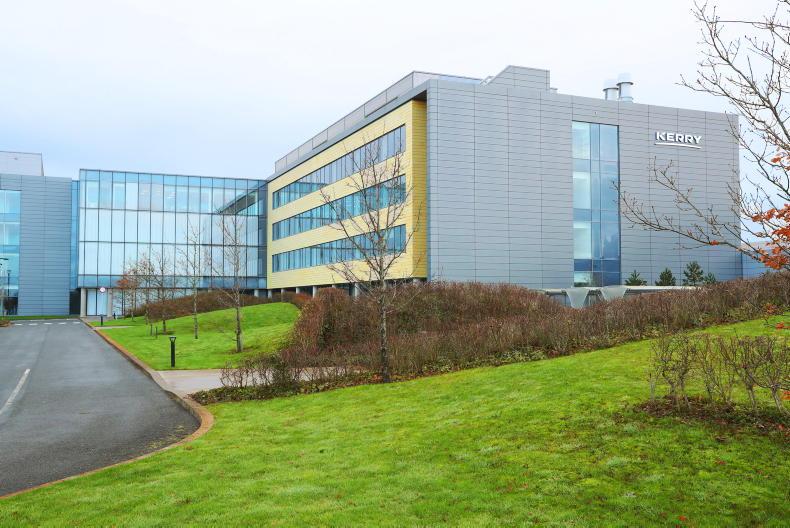

Last week’s trading update from Kerry Group which showed improved performance in the three months to the end of September, coupled with the announcement of another €300m share buyback programme has helped push Kerry shares back towards €100 each.
That is a considerable turnaround from the drop below €65 per share seen only six months ago. It puts the price back close to the level seen in the aftermath of the sale of a majority stake in Kerry Dairy Ireland to Kerry Co-op.
While the better-than-expected performance announced in the trading update and the commitment to continue buying back its own shares from the market have helped the valuation in recent days, the recovery from the March lows was already well underway before last week’s announcement.
Kerry announced an EBITDA (earnings before interest, taxation, depreciation and amortisation) margin target of between 20% and 21% by 2030 and annual sales volume growth of 3% to 5% earlier this year, and the results last week confirm the company remains on track to meet those targets.
Speaking to investors at a recent event in the US, Kerry’s chief financial officer Marguerite Larkins said that the earnings target is based on “the progress we are making and also the opportunity that we see for further margin expansion”.
At the same event, Kerry CEO Edmond Scanlon pointed to the significant growth the company is seeing in the US market.
He said that the company is seeing a lot of business in “renovation” where food products are being reformulated to reduce the amount of salt, sugar and fat contained without changing the taste or texture of the product.
Scanlon said the increase in demand for healthier, more nutritious, foods is being driven by consumer behaviour, helped in part by the increased prevalence of GLP-1 weight-loss drugs such as Ozempic.
The company also sees opportunities for further growth in the US market where retailers are showing greater interest in developing own-label ranges.
While the US does present the best growth opportunities for the company at the moment, Kerry operates across the globe. In the third quarter it saw sales volume growth of 1.3% in Europe and 5.7% in APMEA (Asia-Pacific, Middle East and Africa).
As well as increases in sales volumes, Kerry is expanding its margin through streamlining its operations and the deployment of what the company calls “digital excellence”.
This company-wide programme, titled Accelerate 2.0, aims to achieve €100m in recurring annual savings through reducing the company’s global manufacturing footprint by around 10%, supply chain efficiency and maximising the opportunities from digital and AI.
For 2026, Kerry said that it remains on track to achieve its full-year constant currency earnings per share growth of 6% to 10%.
Shareholders in Kerry Group have been taken on something of a wild ride since the disposal of the controlling interest in Kerry Dairy Ireland. That transaction saw more than €1.5bn worth of Kerry shares transferred to shareholders of Kerry Co-op. In the immediate wake of the transaction, the value of those shares climbed further, topping €100 in the months following the sale.
However, in the subsequent 12 months, that value dropped by more than 45%, taking the value of the initial transfer of shares to close to €1bn – a €500m combined loss of value for those shareholders.
The recent run-up in those share prices is obviously good news for those shareholders. The question for many of them now will be whether it is a good time to sell, or whether they should hold on in the hope of further growth.
While we at the Irish Farmers Journal never give financial advice, it does seem that the company has weathered the recent storm, and has created a compelling story about its future growth prospects.
Recent financial results and market updates suggest it is on the right track for continued growth. If that continues then the performance will be reflected in the share price.