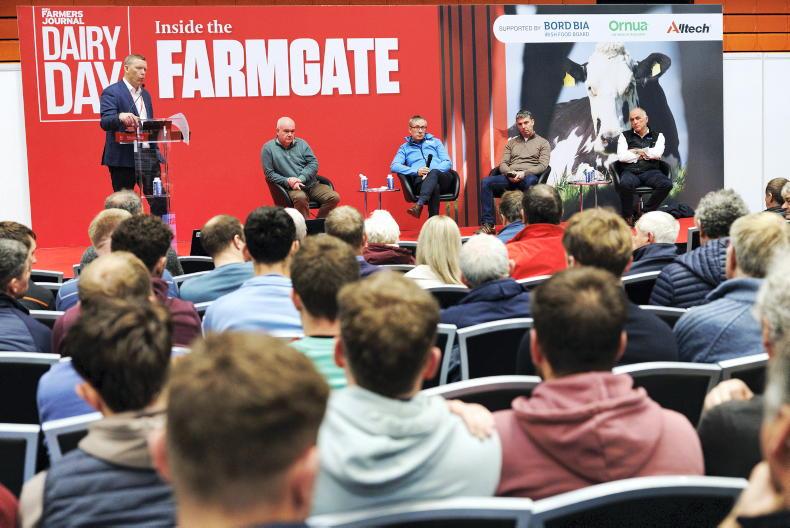

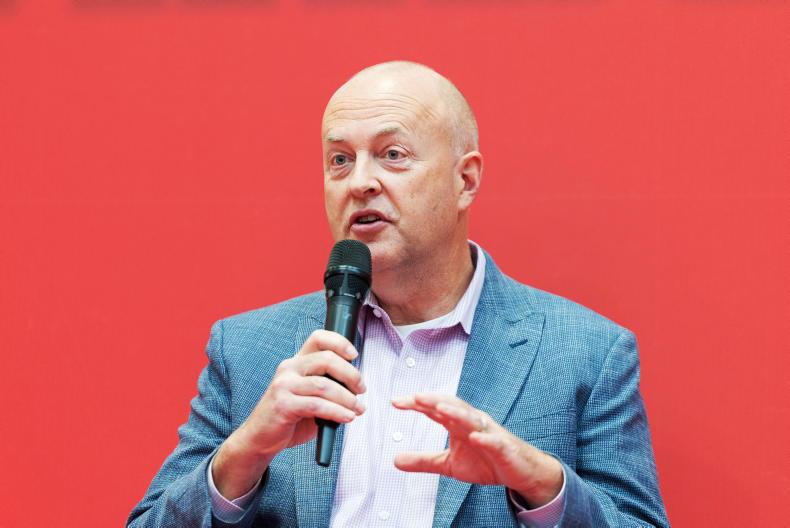
One of the highlights of Dairy Day last week was the outlook for international dairy markets, provided by Mike McCully.
Mike highlighted how growth in US milk production is being supported by high beef prices.
Calves less than a week old are making €1,000/head and while milk production itself is only breaking even with costs, calf sales are providing a strong margin.
There has also been significant investment in US processing capacity to meet growing demand for protein products.
Increased demand from processors should help support US milk prices in the future.
Closer to home, Irish milk supplies have fallen over the last three months. While production across Europe was slower to decline, supplies now appear to be slowing there too.
October milk collection data is not yet available, but production is expected to be down for that month year on year.
GDT
This week’s Global Dairy Trade (GDT) index was unchanged, reflecting the relatively steady nature of European commodity markets.
Cheddar and whole milk powder prices were unchanged this week in Europe, while butter suffered another small setback, falling €75/tonne.
Skim milk powder increased slightly to €3,750/tonne.
A number of co-ops have announced no change to milk prices for October supplies.
Rising energy costs and increased processing costs are being given as the reason for holding.
This is disappointing for farmers, as commodity markets remain relatively steady and European co-ops continue to pay higher milk prices than their Irish counterparts.