
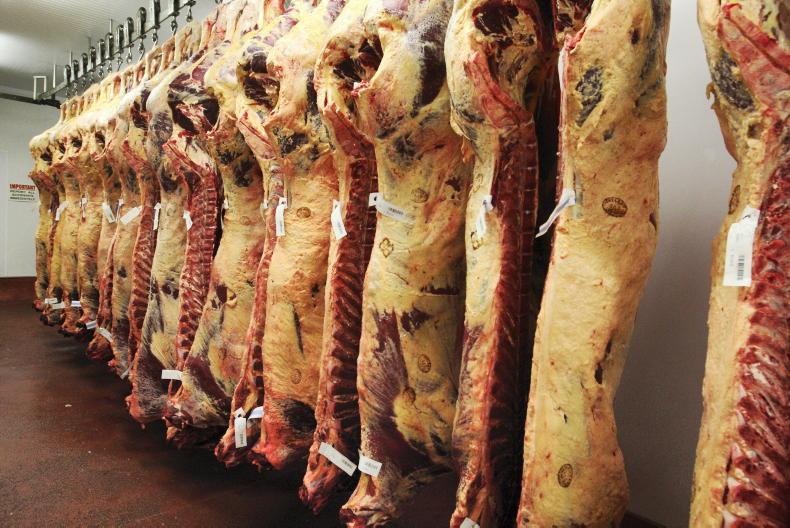
There is more energy in the beef trade this week, with quotes moving upwards in some factories in order to secure cattle.
Factories are now in full Christmas mode processing stock.
Several finishers are reporting that agents wanted cattle a little quicker this week, with some looking for cattle urgently for a number of days.
Base quotes for bullocks are working off €6.60/kg to €6.70/kg, with heifers moving at €6.70/kg to €6.80/kg.
There have been higher prices paid over the weekend, with any finisher with numbers firmly in the driving seat this week.
A top base price of €6.90/kg has been paid to get a load of heifers across the line.
The urgency to get cattle has meant that some bigger finishers finishing cattle on a regular basis have been able to squeeze 20c to 25c/kg above base quotes.
Bonuses of up to 20c/kg are still on the table for in-spec Aberdeen Angus bullocks and heifers, with all-in flat prices around €7.00/kg.
Bulls
Bulls are also solid this week, with under-24-month U grading bulls coming in at €6.70/kg to €6.90/kg, with R grading bulls being bought at €6.60/kg to €6.70/kg.
Under-16-month bulls are working off a base price of €6.50/kg to €6.70/kg. This is before the 12c/kg is applied for in-spec bulls.
Cows
Cows are also in demand, with specialist cow finishers with U grading cows able to squeeze €6.40/kg to €6.50/kg out of the market for well-fleshed heavy U grading cows.
R grading cows are being bought at €6.20/kg to €6.40/kg.
O grading cows are working off a quote of €6.10/kg to €6.20/kg this week, with P+3 cows coming in at €6.00/kg, depending on weight and flesh cover.
Demand isn’t as strong as it was for parlour cows, with some farmers struggling to get cows away in the last 10 days.
Numbers remain tight, with last week’s kill dropping by over 1,000 head. This, coupled with an increased demand, has led to the better appetite for finished cattle this week.
Last week’s kill came in at 35,368 head of cattle, excluding calves, which was back over 1,000 on the previous week’s kill of 36,599 excluding calves.
There was a big drop-off in the number of young bulls processed last week, with a drop of over 700 head.
The bullock kill dropped by just under 350 head, while the heifer kill dropped by just under 300.
Last week’s kill of 35,879 head was almost 4,000 cattle ahead of the same week in 2025. The total kill for 2026 is now running just under 12,000 cattle ahead of the same period in 2025.
Across the water, the beef trade has come under a little pressure, with factories with Irish links leading the charge to get base prices down over the last seven to 10 days.
Base prices are hovering around 635p to 645p/kg (€7.99-€8.12/kg).
UK retail demand remains very strong, with the latest consumer data pointing to increases in mince sales and steak sales.
The latest forecast from Rabobank points to a further decline in beef production across the world in 2027.
While New Zealand and Australia are predicted to go up in production, Brazil – one of the world’s largest beef exporters – is forecast to reduce by 3% in 2027.
The bank expects prices to remain close to current levels, as supplies remain limited on world markets. The Chinese market is expected to recover by 3% in volume after a 10% decline in 2026.
The bank also points to quotas and tariffs redirecting trade flows around the world with higher feed costs and fuel costs affecting margins in 2027.