
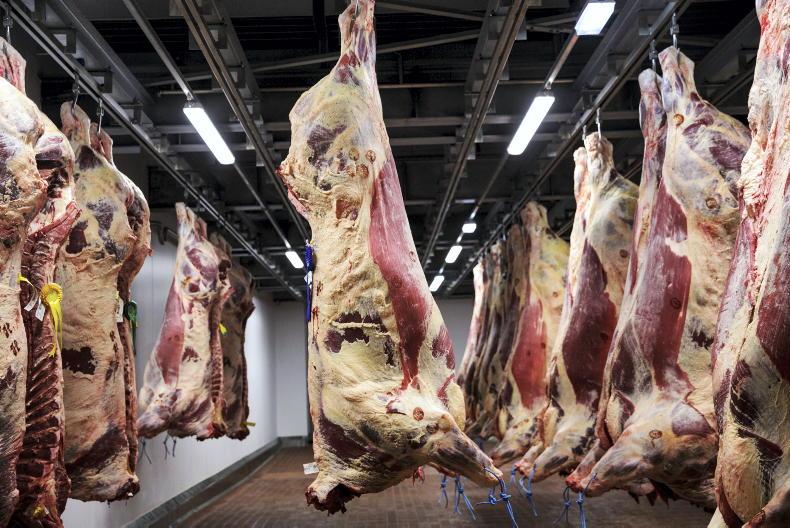
Increased numbers coming on stream has meant factories have used the opportunity to apply some pressure to the beef trade this week.
Factory agents have adopted a little more of a take-it-or-leave-it attitude this week, with some pushing cattle out until the following week.
Most factories have tried to pull quotes by 5c to 10c/kg this week, with some being more successful than others.
There appears to be an abundant supply of Aberdeen Angus cattle available at the moment, with some of the factories that were offering flat prices of €7.20/kg and above it dropping back to €7/kg this week.
With a lot of cattle housed this week, this could mean lower numbers coming on stream for a few weeks.
Bullocks retain the biggest demand, with base prices continuing to hover around the €6.60/kg to €6.70/kg mark.
Most heifers are being bought at a base price of €6.70/kg to €6.80/kg.
Some factories are more anxious for plainer cattle this week, with Friesian bullocks being sought over other stock in some locations.
When purchased on the grid, these are coming in at a lower price to factories and dilute the overall price paid on a given day.
There continues to be a 20c/kg bonus available on top of base prices for in-spec Aberdeen Angus bullocks and heifers.
Bulls
Bulls are also solid this week, with under-24-month U grading bulls coming in at €6.80/kg to €7.00/kg, with R grading bulls being bought at €6.70/kg to €6.80/kg.
Under-16-month bulls are working off a base price of €6.60/kg to €6.70/kg.
U grading cows have firmed up, with €6.50/kg to €6.60/kg now on the table for well-fleshed heavy U grading cows.
O grading cows are working off a quote of €6.10/kg to €6.20/kg this week, with P+3 cows coming in at €6.00/kg to €6.10/kg, depending on weight and flesh cover.
Kill throughput
Last week’s kill was the highest for the year, with almost 37,000 cattle being processed during the week.
The cow kill went up by 500 head to bring the number to 7,571 killed last week.
The bullock kill dropped back slightly to 15,639 head, while the bull kill took the first significant lift in a number of weeks, up over 400 head to 1,789 bulls.
The heifer kill saw one of the biggest lifts, up almost 900 head on the week.
The annual kill to date, having tracked behind the 2025 figure for much of the year, is now within 1,000 head of the same period in 2025.
The bullock kill has seen the biggest change year on year, with 9,000 extra bullocks killed so far in 2026 compared with the same period in 2025.
Britain
In-spec bullocks and heifers in Britain this week continue to trade as high as £6.50/kg (€8.08/kg including VAT).
Young bulls saw the biggest rise in the last two weeks with prices up 6p to 8p/kg.
The latest supermarket purchase information from the UK paints a positive picture for beef sales.
In the 12 weeks to 4 October, UK shoppers spent 1.6% more on beef compared with 12 months ago, with volumes just slightly up at 0.4%.
Steak sales had a good summer sales period, with volumes up 7.9%. Burger sales also saw a lift of 10.2% according to the AHDB.
Further afield, the European Commission has confirmed that it has no plans to reopen the European market to Brazilian beef imports in the short to medium term.
A Commission spokesperson has reiterated the EU stance that Brazil is currently unable to certify that the beef that it exports to Europe meets EU requirements for antimicrobial use.