

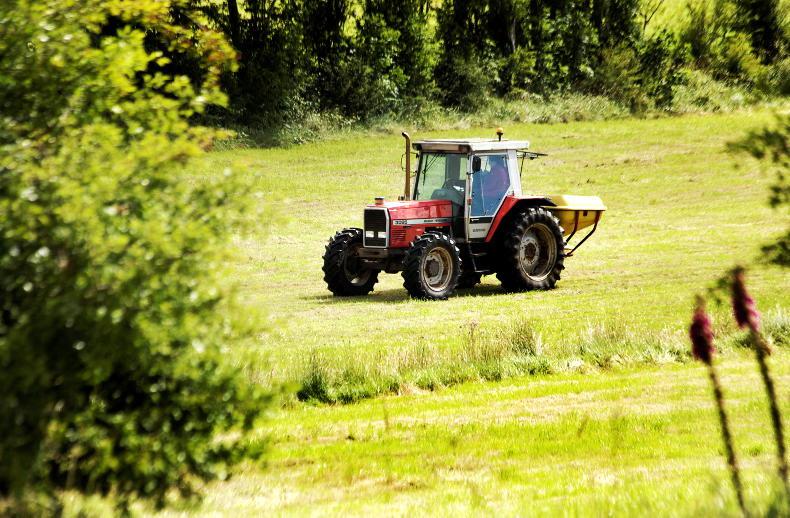
Sales of nitrogen-based fertilisers such as urea and CAN could be back as much as 20% this year.
Last year, around 400,000t of nitrogen, or 1.65m tonnes of fertiliser containing nitrogen, was sold in Ireland.
However, Pat Murphy of Teagasc predicted that a combination of high prices and supply disruption could see nitrogen sales fall as low as 320,000t this year.
While Murphy conceded that there was little empirical data to support this contention and cautioned that the situation could change, he said all the indications pointed to fertiliser sales being well back this spring.
“Fertiliser has been going out a lot slower during February,” explained Teagasc’s head of Environment and Knowledge Transfer.
While price and availability were the primary reasons for reduced fertiliser usage so far this year, Murphy maintained that strong grass covers this spring as a result of good winter growth also helped soften early-season demand.
Some private merchants estimated that fertiliser sales were back 40% to 60% during January and February but have rebounded strongly over the last fortnight as fighting between Ukrainian and Russian forces intensified and the prospect of improved supplies and lower prices evaporated.
The co-ops have experienced a similar surge in demand over the last 10 days.
Glanbia said fertiliser sales were back 25% for January and February, although they were strong in December.
However, a spokesman said farmers were now hunting stock. It is also understood that Glanbia pulled its fertiliser price list due to a backlog of about two weeks on orders in the system.
Lakeland Dairies said fertiliser purchases were back 27% for January and February compared to 2021.
“A larger number of farmers purchased lesser amounts each month through January/February based on an expectation that prices generally might ease back, which would have been hoped for all around,” a spokesman said.
“However, sales picked up considerably over the last few days of February and into early March as there is an expectation that prices may potentially increase further given all of the prevailing market circumstances,” he added.
Farmgate prices are generally unchanged despite the market volatility, with urea on €900/t to €950/t, while up to €1,000/t is being charged for protected urea. Sales prices for 18-6-12 and 10-10-20 are around €760/t and €780/t, respectively.



SHARING OPTIONS