

Last week there were two pieces of news which should provide some relief from rapidly increasing diesel prices.
The Group of Seven (G7) nations agreed a released of diesel and oil from strategic reserves, a move which was closely followed by President Donald Trump announcing that the US would not implement its threatened diesel export ban.
With shipping remaining curtailed through the key Strait of Hormuz water way, transport in the Black Sea practically at a halt, and significant damage done to Russian refinery capacity, the US has become a critical supplier to world diesel markets in recent months.
The recent announcement from Russia that it would keep its own diesel export ban in place until at least the end of October has only increased global reliance on US refineries.
The G7 release of strategic reserves will be helpful in adding more supply to the market, but it is unclear, as yet, how much actual diesel will be coming.
There has been a promise of a “substantial” release of diesel reserves over the 20 days following the announcement.
It is worth noting that an announcement of a release of reserves does not mean it wil limmediately hit the market.
Back in early March there was global agreement to release 400m barrels of oil from reserves. To date, 325m barrels have made their way to the market.
Fundamental
There is also a fundamental problem with releases from reserves. They are the last line of defence when it comes to mitigating the effects of supply shortages.
They are, metaphorically, the last bullet in the gun. Once the reserves are used, there is nothing left for countries to do to try to increase supply. If the diesel reserves are used up now, then there will be nothing to draw on in future.
The chief executive of Saudi Aramco, Saudi Arabia’s state-controlled oil company, recently described the world’s oil stockpiles as “scarily thin” and said that it would take up to two years to rebuild stocks from their current depleted levels.
In effect this means that as well as having to meet future demand for consumption, a return to normal supply patterns will also have to meet extra demand from rebuilding stockpiles.
Therefore, any reduction in fuel costs now will have to be paid for in future, as demand will be stronger than otherwise would be the case, which will keep prices elevated.
When it comes to prices, initial indications from the market suggest that the release from stockpiles has, at best, stopped prices rising even further.
European diesel prices were trading at $1,310/t on Tuesday, pushing the drop since the Friday’s announcment to around 7%. This price is still twice where the commodity started 2026 and 55% above the low seen as recently as June this year.
Taking all these factors together, any sustained drop in diesel prices must be driven by the resumption of global supply from traditional sources, such as the Middle East and Russia.
On the demand side, recent data on volumes of fuel consumption in Ireland does point to some demand reduction in diesel used in motor cars, but little sign of a sustained reduction in marked gasoil demand.
Looking at the latest data from NORA, the national reserve agency, on volumes of oil consumption in Ireland, we can see two clear patterns.
Firstly, as Figure 1 shows, monthly motor diesel consumption has been below recent years in almost every month so far this year. The level reached in August is the lowest for the month in more than a decade.
This points a level of demand destruction, with people choosing to use their diesel cars less, and increasingly switching away from diesel altogether.
This trend is clear in Figure 2, which shows the number of new diesel cars registered between January and August of each year since 2023.
While the vast, vast majority of cars on the road have not been purchased in the last eight months, the very substantial move away from diesel engines does show that consumers are making the choice to avoid using the fuel where possible.
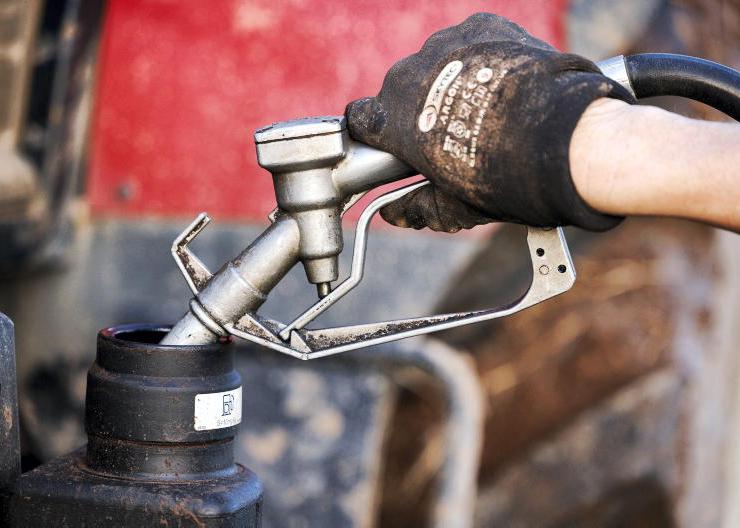
This ‘where possible’ is important when we come to look at consumption of marked gas oil. Here, data from Nora over the past four years shows that consumption in 2026 has been very much in line with recent years.
In fact, looking at Figure 3 we can see that July actually has been one of the highest ever months for low-sulphur green diesel consumption in Ireland.
The fall-off seen in August may well have more to do with the drought conditions in much of the country than the surging price of the fuel.
This difference between changing habits in motor diesel and green diesel consumption has more to do with the lack of alternatives for users of green diesel.
While there are some electric tractors starting to appear on the market, they are nowhere close to the power, capacity or 24-hour availability required from many tractors.
Very few farmers and no contractors are in a position where they can make the shift away from diesel.
Therefore, they are locked into paying higher prices when they occur, with little or no chance of making savings.
This is the reason why green diesel sales have not been hit by high prices to anything like the extent sales of white diesel have.
The release of stockpiles of oil and diesel, coupled with Trump’s walk-back of his threats to halt diesel exports, is good news, as the announcement seems to have slowed the increases in diesel costs for now.
However, without a resolution to the causes of the global shortage of diesel, it seems likely that there will be more prices rises to come further down the line.
Stockpiles are emptying fast, and once they are gone, governments will have nothing left they can do to increase fuel supplies.
This, inevitably, will be reflected in future fuel prices.
Looking at consumption data for Ireland we can already see that when it comes to white diesel, demand has dropped significantly.
Consumers are driving less, and those who can are switching away from diesel powered cars altogether.
For the farming and agricultural contractor, the situation is more difficult as they are neither in a position to do less nor are they able to switch to an alternative fuel source.
This week’s budget included measures in fuel such as the much-expected extension of the cut in excise duties to March of next year.
Farmers will also welcome the top up of the fertilisier support scheme to the maximum level.
However, there wasn’t a huge amount done to ease the burden from green diesel costs.
In the short to medium term Irish farmers and contractors are left hoping that there will be a cessation of hostilities both in the Middle East and Ukraine, which would allow diesel to flow again.
Without that supply, there is no reason to expect lower fuel prices.


SHARING OPTIONS