

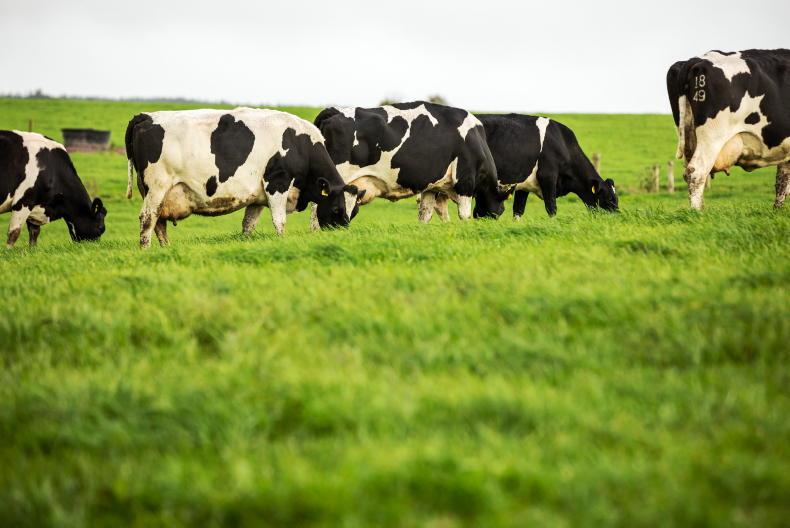
Milk cheques in May and June decide a lot on a dairy farm. They decide a lot in terms of profitability for the year – profitability at both farm and processor level. A milk processor could be top of the milk league from September to February, but it matters little if they don’t pay well over peak.
The dairy sector has never experienced such a significant and severe drop in milk price as it has over the last four months. Yes, milk price was coming from an exceptional high. However, the fall has been extremely sharp.
The January monthly milk league averaged 51c/l. The May league on page 18 averages 37c/l excluding VAT. That’s a drop of 14c/l from January, with some individual processors falling even more. We heard at the Teagasc dairy conference in Decemb?er that on-farm input costs were predicted to reach €2,300 per cow in 2023. A 5,000-litre cow at 37c/l (May average) makes revenue of €1,850 in the year.
Input costs increased 33% in 2022. As expected, 2023 costs have increased further as nitrogen was slow to fall in price, energy costs remained high, feed remained a stubbornly high cost and all other variables that rose on the back of these increases also remained high.
Milk production costs are now higher than what milk suppliers are getting paid for milk. My rule of thumb now is that the cost of production is at 40c/l when you put a nominal value on your own time. For some heavily borrowed farms, this cost will be even higher.
So what will be the impact? Milk supply in 2023 will be challenged. It’s already challenged.
Less bag nitrogen, lower stocking rates and environmental stocking rate quotas are all playing a part in reducing supply and this is before a proposed exit or partial cow cull.
The difficult weather months of March and April will have taken the shine off 2023 volumes to the processor. So costs to the processor are up. Costs to the farmers are up. Commodity product prices have come well down and are just about stabilising now.
The inevitable angry farmer reaction is starting to happen, with Kerry milk suppliers who have been at or near the bottom of the league since January rising into protest last week.
I see farmers taking on a lot of the new science and I struggle to understand the logic of taking out cows from the national herd at this stage
So despite mounting financial pressure reducing supply, we have the fiasco that is an industry grouping continuing to talk about proposals to remove cows from the national herd. I just can’t see the logic in this.
Of course, I understand the legal emissions reduction target of 25% must be met.
However, I see farmers taking on a lot of the new science and I struggle to understand the logic of taking out cows from the national herd at this stage. Yes, we walked ourselves into this by not setting a separate target for biogenic methane. However, that battle is lost now as the 25% overall emissions reduction target for agriculture is enshrined in law.
A couple of points – surely it’s a ruminant cull rather than a dairy cow-only cull? Surely, there are other solutions worth developing before you take the cull option on? Macra’s proposal for a succession-type initiative is worth developing further. If we do go the exit option route then surely we need science to select the cows to maximise the benefit to the environment?
Similar to the new scientific measures on emissions from bogs, we now know modern cows and management are producing much less methane than earlier measurements.
So, after a decade of investment on farm and a decade of investment in milk processing, let’s hope the minister won’t stick this indigenous, long-term profitable industry into reverse by putting a flawed cow cull option on the table.


SHARING OPTIONS